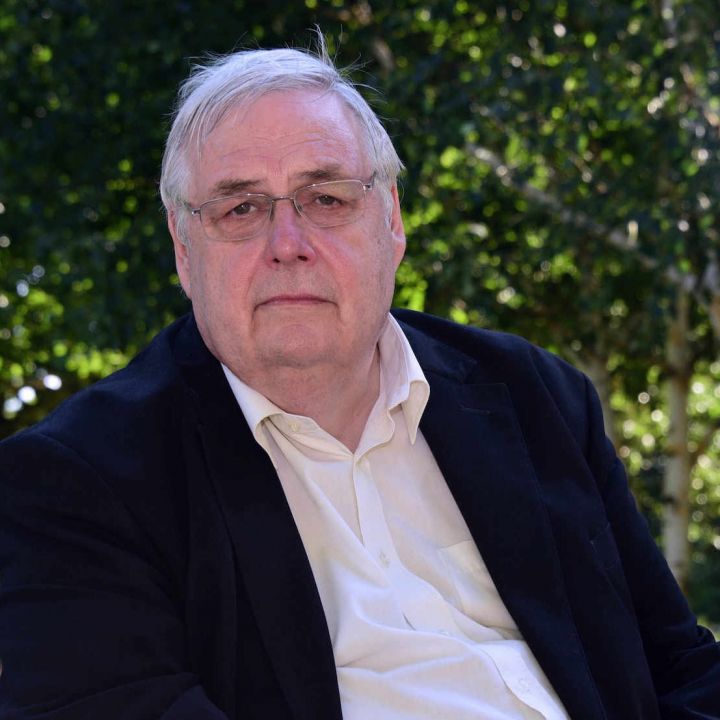
Hartley Foster
Call dates: October 1997
Authorised to practice: England & Wales
Hartley Foster is an independent self-employed barrister registered with the Bar Standards Board of England (ref. no 36917) whose practice is governed by the Code of Conduct of the Bar of England and Wales which code can be found at www.barstandardsboard.org.uk; has full professional liability insurance provided by the Bar Mutual Indemnity Fund Limited (ref BM 2930/078) (details of the world-wide cover are provided at www.barmutual.co.uk); and is registered for VAT (reg. no. 188 8940 36).
About my work as a barrister
The main areas of practice undertaken are in relation to contentious tax (both direct and indirect, including customs duties), this encompasses tax appeals before tribunals and the courts, judicial review and professional negligence matters (claims and defence). In my capacity as an authorised practising self-employed barrister, the work provided is in the form of legal opinion, advice and advocacy.
Contact
The following individuals, are invited to contact me directly for a quote for legal services on: 0208 078 9944 or via e-mail: hfoster@addingtonchambers.com
- Solicitors or other practising lawyers;
- Licensed Access clients, who may either hold a licence issued by the Bar Standards Board, or be a member of a professional body which has been recognised by the Bar Standards Board; and
- Members of the public who wish to instruct a barrister under the Public Access scheme.
I will provide you with a quote as soon as possible. I always aim to set out quotes clearly, but if you receive your quote and there is something you do not understand, please contact me.
Fees
Private client tax work is generally undertaken on fixed fee. This fee will be agreed on a case-by-case basis and will be assessed based on the complexity and volume of work and papers involved in a matter and the amount of time needed to complete the work.
Timescales
Timescales for a case may vary depending on factors, such as: my availability; the type and complexity of the case; the number of papers needing to be reviewed; the need for additional information or documents; the approach taken by the other side; and, the Court or the Tribunal waiting times. The timescale will be discussed with a client at the outset and should anything happen to affect the timescale this will be communicated as soon as possible to the client.
Public Access
If you are a member of the public, the Bar Standards Board’s Public Access Guidance for Lay Clients can be downloaded from the following link:
https://www.barstandardsboard.org.uk/resources/public-access-guidance-for-lay-clients.html.
This will help you to understand how the Public Access scheme works and explains how you can use it to instruct me directly.
Regulatory and Complaints Information
The BSB
Self-employed barristers are regulated by the Bar Standards Board. You can search the Barristers’ Register on the Bar Standards Board’s website: https://www.barstandardsboard.org.uk/for-the-public/search-a-barristers-record/the- barristers-register.html.
The BSB’s Barristers’ Register shows:
- Whether a barrister has a current practising certificate; and
- Whether a barrister has any disciplinary findings, which are published on the Bar Standards Board’s website in accordance with their policy.
Alternatively, you can contact the Bar Standards Board on 020 7611 1444 to ask about this (or e-mail: ContactUs@BarStandardsBoard.org.uk).
Separate information is available on our website which provides information about:
The Data Protection Policy
The Data and Privacy Protection Notice
The complaints procedure
- This procedure sets out any right you may have to complain to the Legal Ombudsman (LeO – the independent body which can help you if you have complained to your lawyer and are not happy with their response); How to complain to the LeO; and any time limits for making a complaint.
- Here is the link to the decision data on the Legal Ombudsman website: https://www.legalombudsman.org.uk/information-centre/data-centre/#ombudsman-decision-data
- This data demonstrates that providers which received an ombudsman decision in the previous 12 months and in each case the data shows whether or not the provider was required to give the consumer a remedy.

Hartley Foster
Hartley is Head of Chambers. Hartley was called to the Bar in 1997. He acts as an advocate, in relation to which he has appeared both on his own and as part of a team in a wide variety of cases, and in an advisory capacity.
Hartley advises in relation to all areas of contentious tax (both direct and indirect, and including customs duties). His practice encompasses tax appeals before the tribunals and courts, judicial review, and professional negligence (claims and defence). He has acted on over 60 reported tax cases, including 4 House of Lords / Supreme Court cases and 5 references to the Court of Justice of the European Union. Hartley also has considerable experience of advising individuals and companies in the context of criminal, or quasi-criminal, investigations undertaken by HM Revenue & Customs.
Hartley’s experience includes establishing and managing specialist Tax Disputes practices at 3 major City solicitors’ firms, each of which practices either won or was shortlisted for the Taxation “Best Tax Team in a Law Firm” or “Best Tax Disputes / Investigations Team” Award.
Practice areas
- Tax
Directory recommendations
Ranked in Chambers & Partners and recommended in Legal 500 for Contentious Tax for over 15 years.
Recently published comments include:
- “The immensely experienced Hartley Foster is heralded by sources as an incredibly safe pair of hands. He is well known for handling HMRC enquiries and negotiations.”
- “He tries to identify new and helpful arguments.”
- “He is a very considered and experienced lawyer.”
- A “brilliant tactician, and extremely diligent and committed.”
- “Hartley Foster is an exceptional lawyer and advises major corporates on heavy hitting tax investigations of the day. He knows the landscape well, is a extremely skilled negotiator who gets results for his clients. Definitely someone who you want on your side when faced with complex tax litigation.”
Example cases
Invamed Group Ltd v HMRC (C-198/15) [2020] EWCA Civ 243
The Court of Appeal held that the electric mobility scooters in issue were correctly classified as “carriages for disabled persons” (thereby attracting a zero import duty).
Higgins v HMRC [2019] STC 2312
The case concerned the meaning of the “period of ownership” in s.222, Taxation of Chargeable Gains Act 1992 in relation to principal private residence relief. The Court of Appeal upheld the taxpayer’s appeal against the decision of the Upper Tribunal that imposed a CGT liability by reference to the period between exchange and completion, noting that “the fact that the construction of the provisions that HMRC favour would rarely entitle ordinary home-owners to full relief from CGT strongly suggests that the construction is incorrect.”
R, on the application of Vacation Rentals (UK) Ltd v HMRC [2019] STC 251
The Upper Tribunal held that the taxpayer had a legitimate expectation that its supplies of card handling services would be exempt from VAT in accordance with HMRC’s published guidance (Business Brief 18/06). It rejected HMRC’s argument that, as the company was a “very sophisticated taxpayer”, it could not be expected to rely on HMRC’s published guidance.
R, on the application of Prudential plc v Special Commissioner of Income Tax [2013] 2 AC 185
The Supreme Court addressed the questions whether legal advice privilege extends, or should be extended so as to apply, to legal advice that is given by someone other than a member of the legal profession. Its answers were “no”.
Countrywide Estate Agents FS Ltd v HMRC [2012] STC 511
The Upper Tribunal held that receipt of a lump sum in return for an exclusivity agreement was an income receipt, rather than being capital in nature, and, accordingly, should be subject to corporation tax.
HMRC v Halcyon Films LLP [2010] STC 1125; HMRC v Micro Fusion LLP [2010] STC 1541
The Court of Appeal held that the statutory film tax reliefs were available to the partnerships in relation to the leasing and further sub-leasing of the film Mrs Henderson Presents.
Re An Application by HMRC to serve a Section 20 Notice on a Financial Institution [2007] STC (SCD) 202; [2007] STC (SCD) 208; [2007] STC (SCD) 216; [2007] STC (SCD) 222
HMRC sought information and documents from banks and financial institutions relating to customers with UK addresses and non-UK bank accounts or credit cards associated with non-UK banks accounts, to assist in relation to its Offshore Disclosure Facility. The Special Commissioner held that there was sufficient evidence to conclude that this ‘class’ of taxpayers was in default and that that had led to serious prejudice to the proper collection of tax.
RCI Europe v The Commissioners for Her Majesty’s Revenue and Customs (Case C-37/08) [2009] STC 2407
The CJEU held that RCI’s services to its members in relation to exchanges of timeshare interests were so closely connected to land that they fell within the special rule in Article 9(2)a of the Sixth Directive (now Article 45 of the Principal VAT Directive), with the consequence that the place of supply was where the member held his underlying timeshare interest, and not, as the UK contended where the supplier belongs (by reason of the general rule in Article 9(1) applying).
R, on the application of Browallia Cal, v City of London General Commissioners [2004] STC 296
The Administrative Court held that s.49(1), Taxes Management Act 1970 bestowed on the General Commissioners a discretion ‘at large’ when considering an application to extend time for lodging an appeal.
Halifax plc v Davidson [2000] STC (SCD) 251; Woolwich plc v Davidson [2000] STC (SCD) 302; Northern Rock plc v Thorpe [2000] STC (SCD) 317; Alliance & Leicester plc v Hamer [2000] STC (SCD) 332
The Special Commissioners allowed the 4 building societies, when calculating their profits, to deduct the expenditure incurred by converting to banks (which amounts had been disallowed on the bases that they were capital in nature (cf. s.74(1)(f), Income and Corporation Taxes Act 1988) and were not incurred “wholly and exclusively” for the purposes of the trade, as required by s.74(1)(a)).
Publications
“Human Rights and Direct Taxes”, Division A1.5 of Simon’s Taxes
“Administrative Machinery”, “VAT – the foundations”, “VAT – UK provisions”, “VAT on property”,
“Practical application of VAT”, “The Impact of EU Law”, Revenue Law; Principles and Practice (21st to 39th editions)
“Disclosure of Tax Avoidance Schemes”, Law and Regulation of Tax Professionals
“HMRC’s Information Powers” and “Tax Appeals”, HMRC Investigations Handbook
“VAT on costs”, Lexis PSL
“HMRC’s Information Powers”, PLC Tax
Regular contributions to periodicals, particularly Tax Journal (over 30 articles published).
Career
Partner and Head of Tax Disputes, Fieldfisher LLP (April 2012 to March 2021)
Partner and Head of Tax Disputes, Olswang LLP (June 2009 to April 2012)
Partner and Head of Tax Disputes, DLA Piper LLP (September 2004 to June 2009)
Barrister, KLegal LLP (renamed McGrigors LLP) (May 2001 to September 2004)
Barrister, Clifford Chance LLP (April 1999 to May 2001)
Regular contributions to periodicals, particularly Tax Journal (over 30 articles published).
Memberships
International Sub-Committee of the Law Society
Revenue Bar Association
VAT Practitioners’ Group
Lifetime Fellow Royal Society of Arts